
What if the cause of the damage matters more than the lead paint itself? If you’re asking, “does homeowners insurance cover lead paint removal,” the general answer is no: insurers often treat removal as maintenance or as work on a pre-existing condition. Coverage may be possible, however, if a covered event, such as a fire or storm, disperses lead dust, or your policy includes a relevant environmental endorsement.
It’s understandable to expect insurance to help with a hazard discovered in your home. But exclusions and policy conditions can make the next step difficult to judge. Coverage depends on what happened, how your policy defines the loss, and whether an exclusion applies. Before assuming either that a claim will be denied or that removal costs will be covered, review your policy and report the circumstances accurately to your insurer.
This guide explains which policy details may affect coverage, what to document after discovering lead paint, and what to ask when reporting the issue. It also explains how professional lead abatement can provide a controlled path forward when removal is needed, regardless of the insurance decision. TSIAC International provides lead abatement, including regulatory-compliance documentation and safe disposal, backed by more than 15 years of industry experience.
Key Takeaways
- For “does homeowners insurance cover lead paint removal,” the answer depends on the cause of the damage and the exact policy terms, not simply the presence of lead paint.
- Review your declarations page, exclusions, and endorsements for language that may affect a lead-related claim.
- Before reporting a concern, avoid disturbing suspected lead-based paint. Organize relevant photos, dates, inspection findings, and repair records.
- Keep the insurance decision separate from the safety response: professional lead abatement can address the hazard whether or not a claim is covered.
Does homeowners insurance cover lead paint removal? Start with the cause
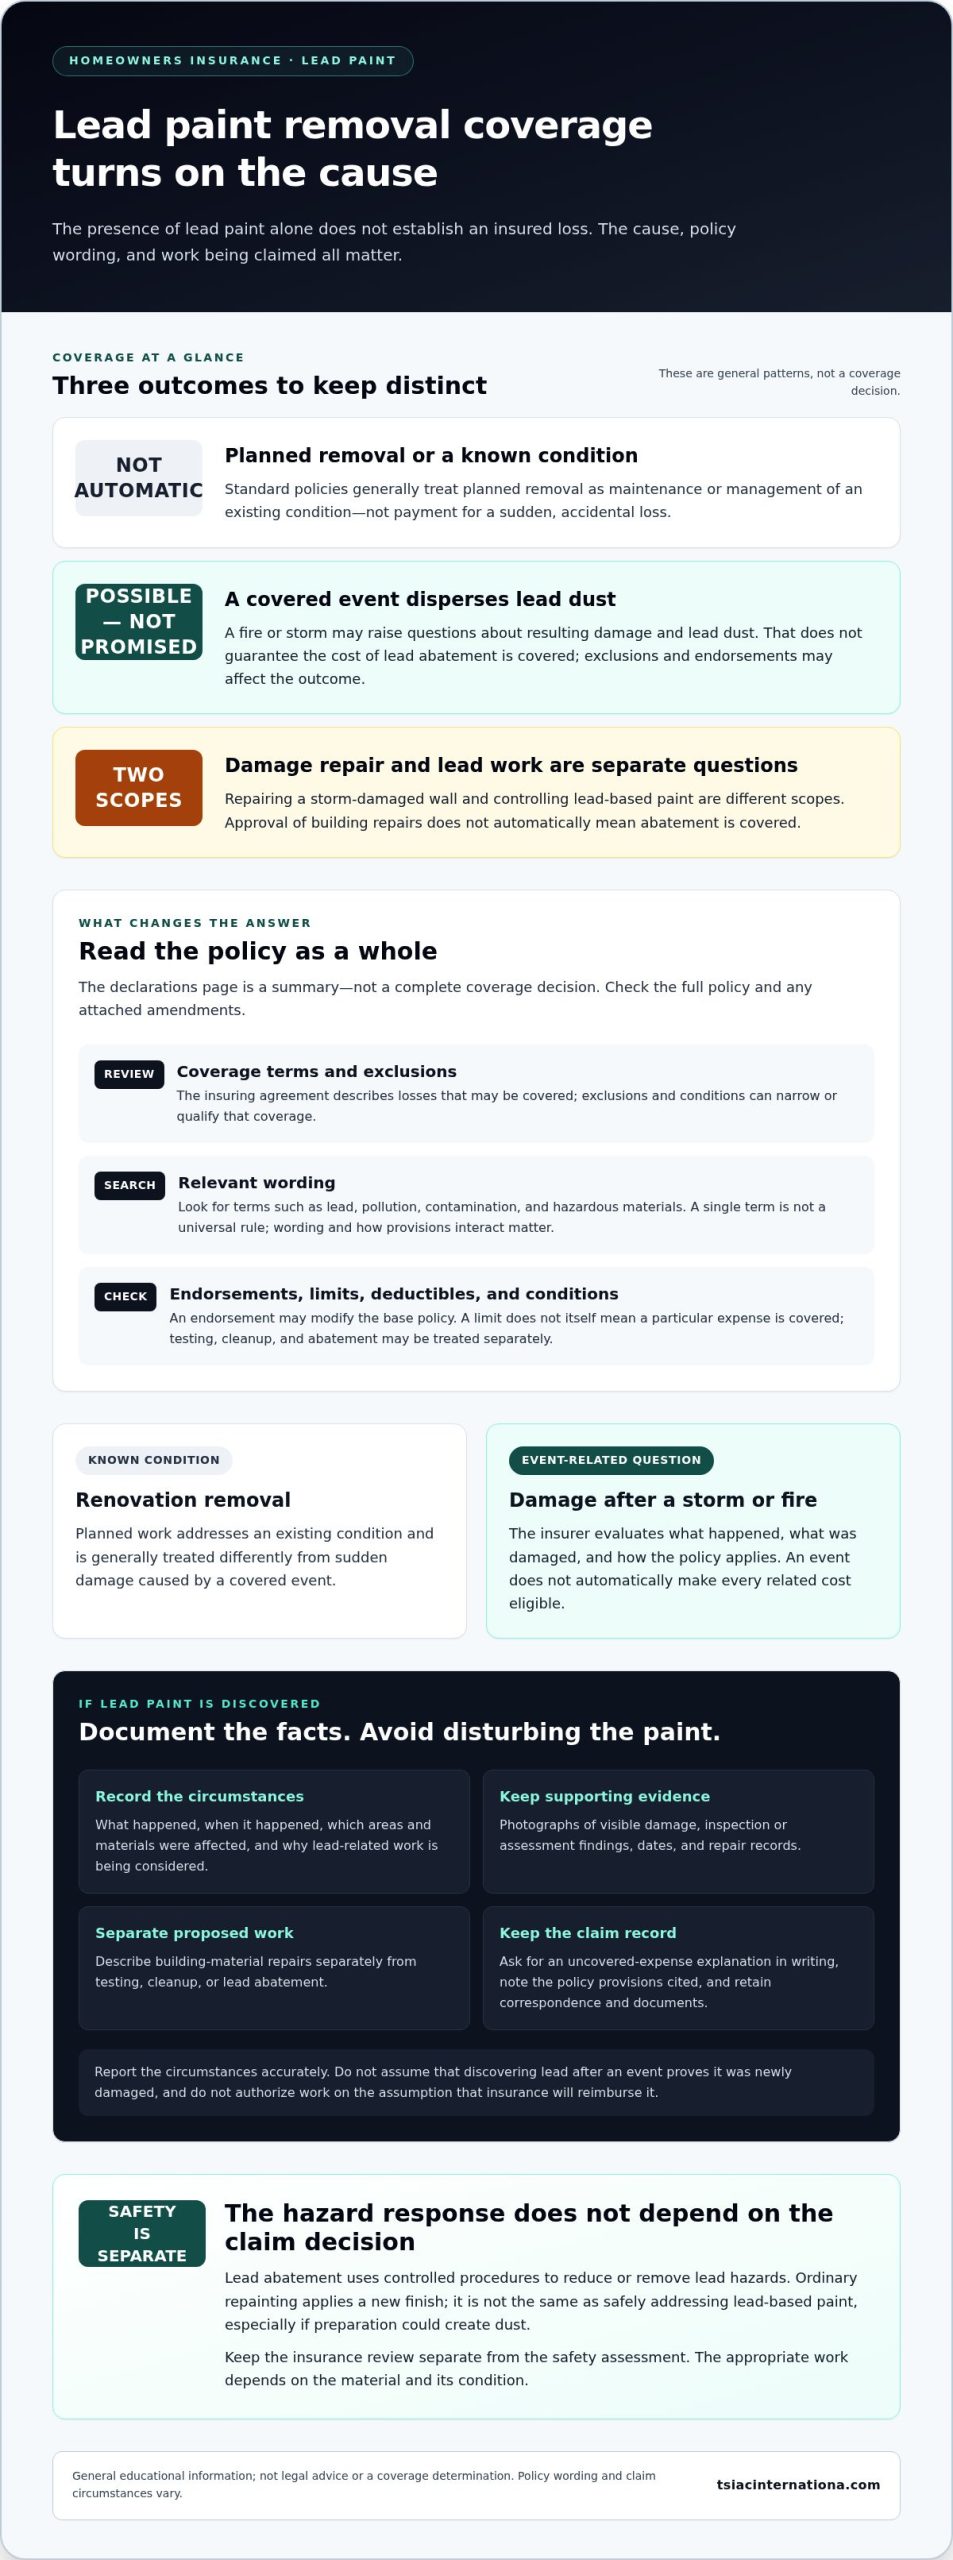
Homeowners insurance doesn’t automatically cover lead paint removal. Coverage depends on the policy, the cause of the damage, and the circumstances of the claim. Standard policies generally treat planned removal as maintenance or management of an existing condition, rather than payment for a sudden, accidental loss. A narrow exception may be possible if a covered event, such as a fire or storm, spreads lead dust, but that doesn’t guarantee the abatement cost will be covered.
Lead abatement uses controlled procedures to reduce or remove lead hazards; ordinary repainting simply applies a new finish. Painting over a surface isn’t the same as safely addressing lead-based paint, especially if preparation disturbs the coating and creates dust. The appropriate response depends on the material and its condition. For historical context on where lead paint was used and the federal housing ban, see Lead-based paint in the United States.
Why the reason for removal matters
A homeowner who schedules removal during a renovation is addressing a known condition. That’s generally different from cleanup after a covered event causes sudden property damage. The presence of lead paint alone doesn’t establish an insured loss. A fire or storm could raise separate questions about resulting damage and lead dust, while exclusions or an environmental endorsement may affect whether related costs qualify. Policy wording varies.
When you describe the loss, explain what happened, when it happened, which materials were affected, and why lead-related work is being considered. Don’t assume that discovering the paint after an event proves it was newly damaged, or that an event automatically makes all resulting work eligible. The insurer assesses the facts against the policy and the reported claim.
Lead paint removal versus damage repair
Separate two potential scopes of work: repairing building materials damaged by an event, and removing or controlling lead-based paint. For example, if a storm damages a painted wall, a claim might involve repairing the wall, while lead-safe work could be considered separately. Approval of one part doesn’t automatically mean the other is covered. The policy terms and the insurer’s evaluation determine how each cost is handled.
Keep records that distinguish the work: photographs of visible damage, descriptions of affected surfaces, inspection or assessment findings, and a proposed scope that separates reconstruction from abatement. This helps show which work addresses physical damage and which addresses the lead hazard. Don’t authorize work on the assumption that insurance will reimburse it. Coverage depends on the insurer’s review of your policy and the circumstances.
Which homeowners policy terms can affect lead paint coverage?
Coverage depends on the policy wording and the facts of the loss. Read the policy as a whole rather than relying on a general description of homeowners insurance. The declarations page summarizes key coverage limits and endorsements, while the insuring agreement describes losses the policy may cover. Exclusions and conditions can then narrow or qualify that coverage.
Start with the declarations page, but don’t stop there. It’s a summary, not a complete coverage decision. The full policy can explain whether an endorsement changes the standard terms, how limits apply, and what duties you must follow after a loss. The answer to “does homeowners insurance cover lead paint removal” can’t be determined from the declarations page alone.
Exclusions, endorsements, and policy limits
Search the policy for terms such as lead, pollution, contamination, and hazardous materials. A pollution or contamination exclusion may be relevant to a lead-related claim, but its wording, scope, and interaction with other provisions matter. Don’t treat a single term as a universal rule. Policy forms and endorsements can differ.
An endorsement may modify or add to the base policy, so review attached amendments alongside the main contract. Note applicable limits, deductibles, and conditions, but don’t assume that a limit means a particular expense is covered. For example, a policy might address physical damage from an event while treating testing, cleanup, or lead abatement separately. The insurer assesses how the provisions apply to the reported loss.
Who decides whether an expense is covered?
The insurer evaluates a claim under the policy contract and the information reported about the loss. Clear documentation helps connect the facts to the relevant terms: identify what happened, when it occurred, which areas were affected, and what work is proposed. A finding of lead paint is important, but it doesn’t replace a review of the cause, damage, exclusions, and endorsements.
If the insurer says an expense isn’t covered, request the explanation in writing and ask which policy provisions support the decision. Compare that explanation with the complete policy, including endorsements, and keep copies of claim correspondence and supporting documents. This article offers general educational information, not legal advice or a coverage determination. Questions about a disputed interpretation may require guidance from a qualified insurance or legal professional.
Insurance review and hazard assessment serve different purposes. The EPA’s Lead Abatement, Inspection and Risk Assessment resource explains the role of assessment in lead-related work. If abatement is needed regardless of the claim decision, TSIAC International provides lead abatement with regulatory-compliance documentation and safe disposal. Learn about lead abatement services.
Lead paint removal insurance scenarios: compare maintenance and covered loss
These examples are illustrative, not coverage decisions. A lead-related health or safety concern deserves attention, but it doesn’t automatically qualify as an insured property loss. Whether homeowners insurance covers lead paint removal depends on the policy language, the cause and timing of the damage, and the work being claimed. Similar situations can receive different outcomes under different contracts.
| Situation | Likely policy question | Information the insurer may need |
|---|---|---|
| Planned renovation or preventive removal | Is this an owner-initiated upgrade or maintenance, rather than repair of a covered loss? Do exclusions or an endorsement address the work? | Why removal is planned, which surfaces are involved, any assessment findings, and the proposed scope of work. |
| Deteriorated or peeling paint | Does the policy address the reported condition, or does it fall under a wear, deterioration, pollution, or maintenance provision? | Where the paint is deteriorating, when the condition was noticed, photographs, and any inspection or repair records. |
| Lead-related work after a sudden event | Is the event covered, and how does the policy treat resulting building damage separately from lead assessment, cleanup, or abatement? | The event date and cause, affected materials, evidence of resulting damage, and separate descriptions of repair and abatement work. |
Preventive removal or renovation work
When an owner chooses to remove lead paint during an upgrade, the insurer may view the expense differently from a repair made necessary by insured damage. A suspected hazard can be a reason to arrange an appropriate assessment and safe work, but it doesn’t by itself establish a covered claim. Review the policy wording, exclusions, and endorsements before drawing conclusions.
Keep the reason for the project clear in your records. Note whether the work is part of a scheduled renovation, responds to deteriorated paint, or follows a particular event. Federal rules address lead-based paint hazards in certain housing contexts, and the applicable scope depends on the situation. The 24 CFR Part 35 Lead-Based Paint Poisoning Prevention regulation provides federal requirements for covered programs and properties, but it doesn’t determine homeowners insurance coverage.
Removal after a sudden property event
If a sudden event damages a painted surface, report the event and describe the observable damage accurately. The insurer may evaluate the cause, building repairs, and proposed lead-related work as distinct parts of the claim. For instance, approval to repair a damaged wall wouldn’t establish that testing or abatement is also covered. Ask how the insurer wants the work documented and whether it needs more information before repairs proceed.
Don’t assume that a similar scenario guarantees the same outcome for your claim. Submit relevant records and request a coverage decision based on your policy and circumstances. If abatement is needed for safety, that work addresses the hazard; the insurance decision addresses payment under the contract. Keep those questions separate as you plan next steps.
How to respond when you discover lead paint and may file a claim
Finding suspected lead-based paint calls for two parallel actions: protect people from exposure and handle any potential insurance claim in an orderly way. Don’t sand, scrape, drill, or otherwise disturb the paint while arranging an appropriate assessment. A claim decision can take time, so don’t delay safety steps solely because you’re waiting to hear whether insurance will pay.
Document the condition and review the policy
Record what you can observe without touching the surface. Photograph the affected area from a safe distance, note when and where you noticed the condition, and gather related inspection findings and repair records. Collect the declarations page, complete policy, endorsements, and prior assessments so you can report the situation accurately and refer to the actual contract.
- Limit disturbance. Keep people away from visibly deteriorated areas where practical, and don’t attempt a do-it-yourself test or repair that could create dust. Arrange an appropriate assessment to determine what the material is and what response is warranted.
- Create a dated record. Note the location, visible condition, discovery date, and any event you believe may have caused damage. Take photographs without scraping or moving paint chips.
- Collect supporting documents. Save inspection findings, repair estimates, receipts, maintenance records, and relevant correspondence. If work is proposed, keep the scope for lead-related work distinct from estimates for repairing other building materials.
- Read the full policy. Keep the declarations page, insuring agreement, exclusions, endorsements, and claim instructions together. Record questions about specific terms rather than relying on a brief summary of coverage.
- Check applicable requirements. Federal and state requirements can depend on the property and the work involved. Verify current rules before assuming a particular compliance duty applies to your situation.
Notify the insurer and protect occupants
If an event may have caused property damage, notify the insurer promptly using the process stated in your policy. Explain what happened and what you observed, and distinguish known facts from concerns that still need assessment. Ask which records are needed, how to submit them, and whether the insurer wants to inspect before repairs begin.
Keep a dated log of calls, names, instructions, and decisions, and retain copies of everything you submit. If coverage is denied or limited, request the insurer’s explanation in writing and note the policy provisions it identifies. This creates a clear record without treating an initial conversation as a final determination of whether homeowners insurance covers lead paint removal in your specific case.
Insurance reporting and lead hazard control are separate processes. Continue arranging an appropriate assessment and safe abatement plan while the insurer reviews the claim. Don’t disturb suspected paint to speed up either process. TSIAC International provides lead abatement with regulatory-compliance documentation and safe disposal. Learn about professional lead abatement.
When lead abatement is needed, TSIAC provides a controlled project path
An insurance decision determines whether a policy may pay for certain expenses. It doesn’t remove a lead hazard or define the work needed to address it. If an assessment indicates that lead abatement is necessary, the property still needs a safe, organized response, whether or not an insurer approves related costs.
TSIAC International provides lead abatement for residential and commercial properties, backed by more than 15 years of industry experience. The project scope depends on the property’s conditions and the work required. Professional abatement may involve controlling the work area, removing or otherwise addressing affected materials through controlled procedures, and handling resulting waste safely. The specific approach is determined by the project, not by a general description of lead paint.
What professional lead abatement addresses
Lead abatement is more than applying a fresh coat of paint. It addresses lead hazards through planned work that considers affected materials, the work area, and safe handling of waste. Avoid attempting to sand or scrape suspected lead-based paint yourself; disturbing it can create dust. An appropriate assessment helps establish the condition and inform the remediation scope.
TSIAC International’s lead-abatement service includes regulatory-compliance documentation and safe disposal. These records help clarify what work was undertaken and how related materials were handled. Property owners planning hazardous-material work can benefit from understanding how assessment, work scope, and documentation fit together before remediation begins.
How abatement fits into a property claim
Keep three decisions distinct: the insurer determines coverage under the policy, the claim process determines whether and how payment is made, and the abatement work addresses the lead hazard. A project scope or documentation doesn’t establish insurance approval, and an insurance decision doesn’t replace a safety assessment.
If the work is connected to a claim, maintain a clear file with assessment findings, the scope of work, relevant photographs, completion records, and disposal documentation. TSIAC International provides project documentation as part of its lead-abatement service, giving property owners a record of remediation work to keep with claim correspondence. The insurer makes its own coverage determination based on the policy and reported facts.
For a property where lead abatement is needed, TSIAC International provides documented remediation work. Contact TSIAC International to discuss lead abatement for your property.
Move forward with a clear plan for your property
The question “does homeowners insurance cover lead paint removal” is only one part of deciding what to do next. While the insurer reviews a claim, arrange an appropriate assessment and plan any necessary work without disturbing suspected lead paint. Keeping claim records separate from remediation records can help you track both processes and make informed decisions as new information becomes available.
If lead abatement is the next step for your home or commercial property, TSIAC International can discuss the project and the controlled remediation work it may require. Discuss a lead abatement project with TSIAC International.
Frequently Asked Questions
Does homeowners insurance cover lead paint removal in every situation?
No. A policy doesn’t automatically pay for lead paint removal, and the presence of a lead hazard alone doesn’t establish coverage. Insurers generally distinguish planned upkeep from costs tied to a covered event, while exclusions or endorsements may affect the result. Review the complete policy and ask the insurer how its terms apply to your circumstances, especially if your policy includes an environmental endorsement.
Will homeowners insurance pay to remove lead paint during a renovation?
Usually, an owner-planned renovation is treated differently from repairs following an insured event, so don’t assume the removal will be reimbursed. Before work begins, identify which expenses relate to the renovation and which, if any, address documented damage. Ask the insurer whether it needs records or an inspection, and organize estimates and invoices by work type to clarify what each expense covers.
Can homeowners insurance cover lead paint removal after a covered water or fire loss?
Possibly, but coverage depends on whether the specific event is covered and how the policy treats resulting lead-related work. For example, a policy might address repairs to damaged drywall differently from cleaning or abatement. Report the event and describe the affected materials accurately. Ask the insurer to assess each part of the proposed work separately rather than assuming approval of one repair covers all related costs.
Does homeowners insurance cover medical expenses from lead exposure?
Homeowners insurance isn’t health insurance, so don’t assume it will pay for medical evaluation or treatment. Contact a healthcare professional about exposure concerns and review your health plan for questions about medical expenses. A separate liability issue could arise if another person alleges harm connected to the property, but lead-related liability may be excluded or limited. Check the policy wording and request the insurer’s explanation.
What happens if my insurer denies a lead paint removal claim?
Request the denial and the policy provisions supporting it in writing. Compare the cited language with your complete policy, including endorsements, and check whether the decision addresses each claimed expense separately. If you have additional documentation, ask how to submit it for reconsideration. You can also contact your state insurance department for information about complaint procedures. A qualified insurance or legal professional can help explain your options.
Does landlord insurance cover lead paint removal in a rental property?
Not automatically. Landlord policies may contain specific exclusions for lead liability claims involving tenants, while property-damage coverage presents a separate question. Review both the liability and property sections, including endorsements that address lead, pollution, or hazardous materials. Keep maintenance records, tenant communications, and assessment documents organized. If a tenant reports a concern, follow the policy’s claim process while taking appropriate steps to address the reported safety issue.
Do I need to remove lead paint before selling my home?
Federal rules generally require sellers of most housing built before 1978 to disclose known lead-based paint and related hazards; they don’t generally require removal solely because a home is being sold. Federal requirements also provide buyers time to arrange an inspection. Requirements can depend on the property and transaction, so check current federal, state, and local rules and keep relevant inspection or remediation records available during the sale.
Can I stay in my home while lead paint abatement is underway?
It depends on the affected areas, project scope, and controls established for the work. Some projects may restrict access to specific rooms, while other circumstances may call for occupants to stay elsewhere temporarily. Don’t assume the home is safe to occupy during active work. Follow project-specific access instructions, particularly for children or others who may be more vulnerable to lead exposure, and wait for clearance instructions before re-entering restricted areas.
